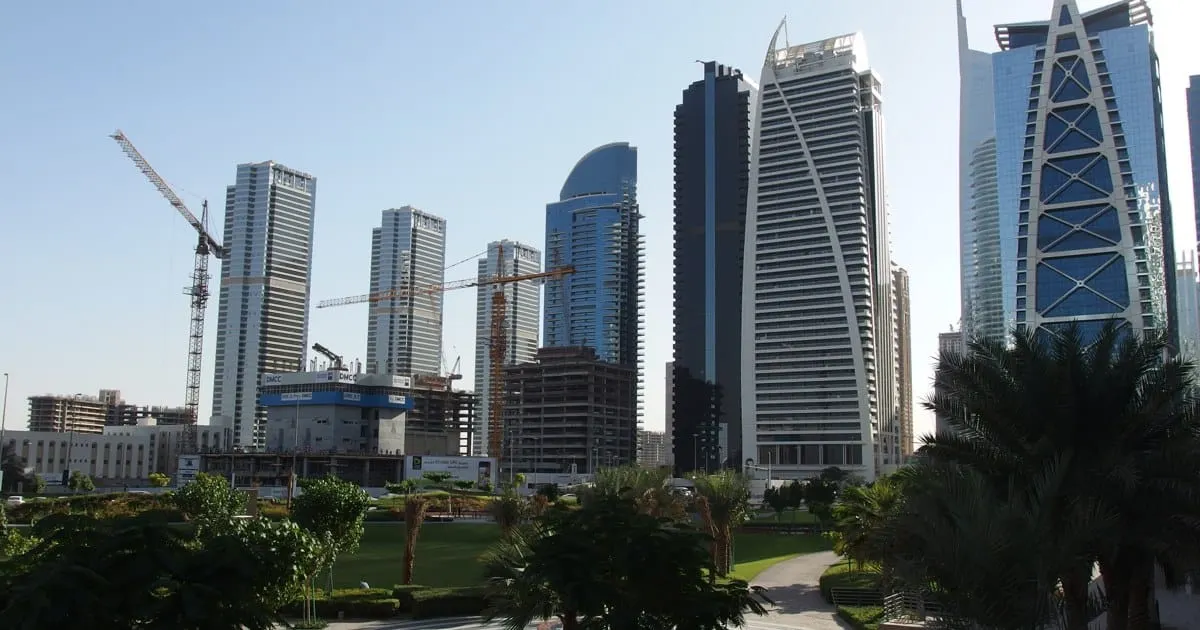
Many founders and families end up owning several things at once: an operating company, a stake in another business, perhaps some intellectual property. Sooner or later they want one clean company at the top that holds it all. DMCC, the Dubai free zone around Jumeirah Lakes Towers, now offers two licences built for that job.
The first is the special purpose vehicle, or SPV. The second is the holding company. Both are for owning things rather than trading. And neither needs a physical office in DMCC.
This guide explains what each licence allows, how they differ, what they cost, how they're taxed and when DIFC or ADGM may suit you better. For the wider picture, start with our overview of UAE wealth structuring in 2026.
Key Takeaways
- A DMCC SPV holds specific assets. It can't trade, and it needs no company secretary and no annual general meeting.
- A DMCC holding company is for owning and controlling a group. It must prepare group accounts as well as its own. DMCC's SPV page, Licensing Rules and List of Approved Activities don't say whether either licence can employ staff.
- DMCC says neither licence needs a physical office. An SPV still needs a registered office address, which can be its service provider's.
- DMCC advertises a starting price of AED 3,690 (about USD 1,005) and doesn't say what it covers. Treat it as a starting price, not as a government fee. Legal, service provider (registered agent), administration, accounting and audit fees come on top.
- Holding shares for at least 12 months can count towards the 0% free zone tax rate. Income from Dubai residential or mainland property generally can't. Take tax advice on your own facts.
In this article:
- What are the DMCC SPV and holding company licences?
- SPV or holding company: what's the difference?
- What can you put in a DMCC SPV?
- Do you need an office or staff?
- What does it cost?
- DMCC, DIFC or ADGM for a holding vehicle?
- How is a DMCC SPV or holding company taxed?
- SPV, holding company, foundation or family office?
- Who should choose DMCC, and who should look elsewhere?
- Frequently asked questions
- Next steps
- Sources and legal references
What are the DMCC SPV and holding company licences?
They're two licences for DMCC companies that own and control assets rather than run a business.
DMCC wrote both into its rules in its October 2024 overhaul and launched them publicly in May 2025. Each sits in DMCC's Commercial Licence category, alongside the single and multi family office licences.
The company itself is an ordinary DMCC company. It can be limited by shares (an LLC) or limited by guarantee (a CLG, where members promise a fixed sum instead of buying shares), according to DMCC's SPVs and Holding Companies page. DMCC asks you to set one up through one of its licensed registered agents, service firms it has approved to handle applications.
DMCC pitches the pair at groups, family offices and investors. Ahmed Hamza, Executive Director of the Free Zone at DMCC, said the licences "make it easier to manage investments, protect assets, and oversee operations across markets."
SPV or holding company: what's the difference?
Choose an SPV to hold a specific asset; choose a holding company to own and control several businesses from one place.
DMCC describes the SPV as a way to manage specific assets without the complexity of trading. It keeps an asset apart from your main business. The holding company is meant to sit on top of several businesses and control them from one place.
| Item | DMCC SPV | DMCC holding company |
|---|---|---|
| Can it trade? | No | Not stated by DMCC's page or rules |
| Can it hire staff? | Not stated by DMCC's page or rules | Not stated by DMCC's page or rules |
| Physical office in DMCC? | Not required; registered office address needed | Not required, per DMCC |
| Company secretary and annual general meeting | Not required | No exemption listed; ordinary company rules apply |
| Group (consolidated) accounts | Required if it owns subsidiaries | Required, on top of its own accounts |
| Typical use | Holding a specific asset: property, intellectual property, a securitisation or structured finance transaction | Owning and overseeing several subsidiaries and investments |
The practical test is simple. If the company only needs to hold one asset, an SPV is the lighter tool. If several companies need one owner at the top, the holding company licence is built for that. DMCC's SPV page, Licensing Rules and List of Approved Activities don't say whether either licence allows staff, so ask DMCC before you plan a team. Our guide to UAE holding company structures covers how this top layer fits a wider group.
What can you put in a DMCC SPV?
Almost any asset you want to ring-fence, as long as the SPV only holds it and doesn't run a business.
DMCC gives examples: real estate and intellectual property on its SPV page, asset holding, securitisation and structured finance in its launch announcement, and debt or equity securities in its List of Approved Activities. Shares in other companies fit too, since DMCC's activity list names equity securities among SPV assets.
A worked example
Say you own a trading company in DMCC and a 20% stake in a European business you've held for three years. Today you own both personally. You set up a DMCC holding company and move both shareholdings into it. Moving shares you own personally into a company can itself be taxed where you live, so check that first.
The holding company now sits above your trading company and the European stake. Dividends flow up to it. If you later sell the European stake, the sale happens at holding level, not in your own name.
If one holding layer is enough, an SPV could hold the same shares.
Now say you also want to put a Dubai apartment into the structure. Be careful here for two reasons.
DMCC doesn't publish whether its SPVs can own freehold property in Dubai outside DMCC, so check with the Dubai Land Department and DMCC before you buy. And the tax rules as written suggest the rental income wouldn't get the 0% free zone rate. More on that below.
One more open point: DMCC's SPV page doesn't say whether individuals can own an SPV directly or only companies can. Confirm the ownership you have in mind with your registered agent early.
Do you need an office or staff?
No office for either licence, according to DMCC. DMCC's SPV page, Licensing Rules and List of Approved Activities don't say whether either licence can employ staff.
Ordinary DMCC licences need a lease or freehold in DMCC (DMCC Licensing Rules). The rules allow DMCC to waive this, and DMCC has done so for these two licences. Its SPV page lists "no physical office required" as a benefit for both.
An SPV must still keep a registered office address. That can be the address of a corporate service provider registered with DMCC.
On people, the same three documents say nothing for either licence. Ask DMCC before you plan to employ anyone.
DMCC doesn't publish how many visas, if any, a holding company without an office can sponsor. If residence visas for you or your team matter, confirm this with DMCC before you commit.
What does it cost?
DMCC advertises a starting price of AED 3,690, about USD 1,005, without saying what it covers or whether it is a government fee. Legal, service provider, administration, accounting and audit fees come on top.
That figure appears on DMCC's SPV and holding company page. DMCC doesn't say whether it's the licence, the registration or a package. It also doesn't say whether the price differs between an SPV and a holding company.
DMCC's schedule of charges has no line for either licence. We checked both on 9 and 10 November 2026.
Whatever the set-up figure turns out to be, expect these recurring items:
- the licence, renewed on or before it expires (DMCC doesn't publish the renewal fee for these licences);
- a registered agent, since DMCC routes set-up through its licensed agents;
- a registered office address, which a service provider can supply;
- annual accounts to international accounting standards (IFRS), audited by a DMCC-approved auditor and filed with DMCC (DMCCA Company Regulations);
- group accounts as well, for a holding company or any SPV that owns subsidiaries.
The audit is easy to overlook. We found no audit exemption for SPVs in DMCC's rules. The only built-in exemption is for a company that was dormant for the whole year, and DMCC can waive the rules case by case (DMCCA Company Regulations). Plan for an annual audit.
DMCC's List of Approved Activities gives a minimum share capital of AED 50,000 for both the SPV and the holding company activity. Ask your registered agent before you budget.
The AED 3,690 is DMCC's starting price; DMCC doesn't say whether it is a government fee. Legal advice, the registered agent's service fee, administration, accounting and the audit come on top. They vary with the provider and the complexity of your structure.
DMCC, DIFC or ADGM for a holding vehicle?
DMCC has the lowest advertised starting price; DIFC and ADGM publish clearer fee tables, including renewals. In all three, professional fees come on top.
The two financial centres also offer holding vehicles. In DIFC, the usual tool is the DIFC prescribed company. In ADGM, it's the ADGM SPV.
| Item | DMCC SPV or holding company | DIFC prescribed company | ADGM SPV |
|---|---|---|---|
| Registry fee or starting price, year one | From AED 3,690 (about USD 1,005); scope not stated | USD 1,100 | USD 1,900 |
| Registry fee, later years | Not published | USD 1,300 | USD 1,400 |
| Professional fees (legal, registered agent or service provider, administration, accounting, audit) | Extra; not published | Extra; not published | Extra; not published |
The DIFC and ADGM figures are registry fees. DMCC's figure is a starting price of unstated scope. ADGM itself notes that third-party provider fees vary from provider to provider. In every centre, legal, service provider, administration, accounting and audit fees come on top.
The DMCC figure is also the least certain of the three, because DMCC doesn't say what it includes. For the detail on the two financial centres, read our comparison of the DIFC SPV and the ADGM SPV.
How is a DMCC SPV or holding company taxed?
It can pay 0% on qualifying income if it meets the free zone conditions; otherwise the standard UAE corporate tax applies.
The UAE taxes companies at 9% on profits above AED 375,000, and 0% below that. A free zone company can pay 0% on its qualifying income instead. To get there, it must be a qualifying free zone person, meaning, among other conditions, it:
- has adequate substance in the UAE;
- prepares audited accounts;
- keeps its non-qualifying revenue small: no more than 5% of total revenue or AED 5 million, whichever is lower.
The law asks for adequate substance in the UAE but gives no simple test. Broadly, the company's real work and decisions should happen here, with the resources its activity needs.
If it fails a condition, it loses the 0% rate for that year and the next four.
DMCC's own summary is shorter: its members "remain eligible for a 0% UAE Corporate Tax rate when meeting certain conditions."
Holding shares can qualify
Good news for holding structures: holding shares and other securities for investment counts as a qualifying activity. The rules treat shares as held for investment when you keep them for at least 12 months without a break (Ministerial Decision No. 229 of 2025). So a DMCC holding company or SPV that owns shares long term can, in principle, earn 0% on that income.
Substance deserves a close look. DMCC says neither licence needs a physical office, so how your SPV or holding company will show adequate substance in the UAE is a point to settle with your tax adviser before you set it up.
Property income is different
Owning or exploiting real estate is an excluded activity. The one carve-out is commercial property in a free zone, where the deal is with another free zone business. The rules as written suggest an SPV holding Dubai residential property or mainland real estate shouldn't expect 0% on that income.
Dividends and gains from subsidiaries
A separate relief, the participation exemption, can take dividends and share-sale gains out of tax altogether. In plain words, it generally applies where:
- you own at least 5% of the company, or your stake cost more than AED 4 million;
- you hold it, or intend to hold it, for 12 months without a break;
- the company you own pays corporate tax of at least 9% where it's based, or is itself a qualifying free zone person (Federal Decree-Law No. 47 of 2022).
If you sell before the 12 months are up, the exempt income can be taxed after all (Federal Decree-Law No. 47 of 2022). Dividends from companies resident in the UAE are exempt without these conditions.
Apply this to the worked example. Dividends from the DMCC trading company would be exempt as UAE dividends. Dividends from the 20% European stake could be exempt if the European company pays at least 9% tax at home. That's a question of fact for each company, so check it.
These are readings of the rules, not guarantees, and the interaction between the reliefs can be technical. Take tax advice on your own facts. Our guides to UAE free zone corporate tax and UAE corporate tax explain the wider system.
SPV, holding company, foundation or family office?
Use an SPV or holding company to own businesses and assets; use a foundation or family office when the goal is family control and succession.
The four tools do different jobs:
- SPV: holds a specific asset, without trading.
- Holding company: owns and controls a group from the top.
- Foundation: has no shareholders, so it can own the holding company and pass control between generations under its own rules. See our DMCC foundation guide.
- Single family office: manages one family's wealth in-house. See our guide to the DMCC single family office.
They often work together. A family might keep a foundation at the top, a holding company beneath it and SPVs for individual assets, all within one free zone and one registrar, once DMCC opens foundation applications (not yet open on 8 November 2026).
Who should choose DMCC, and who should look elsewhere?
DMCC suits owners who want an office-free holding layer in Dubai; look elsewhere if you need a fully published fee schedule or tax-free property income.
DMCC may suit you if:
- your operating companies already sit in DMCC;
- you want to hold shares or intellectual property without renting an office;
- you want one company at the top that owns and controls your group;
- a low advertised starting price matters to you, bearing in mind that legal, service provider, administration, accounting and audit fees come on top.
It may be worth looking elsewhere if you need:
- a published renewal fee before you commit, which DIFC and ADGM provide;
- 0% tax on Dubai residential or mainland rental income, which the rules as written don't give;
- certainty on visas for the owner or staff, which DMCC doesn't publish for these licences;
- an operating business, which needs an ordinary trading or service licence.
For a broader comparison of zones, see our guide to the best free zones in the UAE.
Frequently asked questions
How much does a DMCC SPV or holding company cost?
DMCC advertises a starting price of AED 3,690, about USD 1,005, without saying what it covers or whether it differs between the two licences. DMCC doesn't say whether that is a government fee; legal, service provider (registered agent), administration, accounting and audit fees come on top.
Also budget for licence renewals, a registered office address and IFRS accounts with an annual audit. DMCC doesn't publish the renewal fee.
Can a DMCC SPV own property in Dubai?
DMCC lists real estate as a typical SPV asset. But it doesn't publish whether an SPV can own freehold property in Dubai outside DMCC. Check with the Dubai Land Department and DMCC before you buy, and take tax advice, since rental income from residential or mainland property generally doesn't get the 0% free zone rate.
Can I get a residence visa through a DMCC SPV or holding company?
DMCC's SPV page, Licensing Rules and List of Approved Activities don't say whether either licence can employ staff or sponsor visas. Confirm your visa position with DMCC before you commit.
Does a DMCC holding company pay 0% corporate tax?
It can on qualifying income, such as dividends and gains from shares held for at least 12 months (Ministerial Decision No. 229 of 2025), if it meets the free zone conditions. Income from Dubai residential or mainland property is generally excluded. Take advice on your own facts.
Next steps
Start with a map. List what you own, who owns it today, and whether you are holding one asset or owning several companies. That tells you whether an SPV or a holding company fits, and whether DMCC is the right home.
Then check three things before you commit: what the DMCC starting price covers (legal, service provider, administration, accounting and audit fees come on top), how the audit and substance will work, and whether any property sits in the structure. Ancova structures and administers UAE foundations and holding companies. If you'd like to test the DMCC route against your own assets, book a structuring consultation.
Sources and legal references
- DMCC SPVs and Holding Companies page, checked 10 November 2026 (starting price AED 3,690, no physical office required, set-up through a DMCC registered agent).
- DMCC press release, "DMCC unveils new SPV and holding company licences to enhance business structuring", 5 May 2025. Quote by Ahmed Hamza, Executive Director, Free Zone, DMCC.
- DMCC Licensing Rules, version 3. Commercial Licence: Rule 3.1.1(c). SPV: Rule 3.1.2. Holding company: Rule 3.1.5. Lease or freehold requirement and paid-up capital: Rules 3.2.1 and 3.2.3.
- DMCCA Company Regulations 2024, updated 2 January 2025. SPV exemptions from secretary and annual general meeting: Articles 56.2 and 60.2. Accounts and audit: Articles 73.2, 73.3 (group accounts for any company with subsidiaries), 73.4, 73.6, 73.7, 78.1 and 78.11. Waiver: Article 77.1.
- DMCC schedule of charges, checked 9 November 2026. No SPV or holding company line.
- DIFC Registrar of Companies table of fees, DIFC-CS-GL-03 Rev. 16, 30 July 2026. Prescribed company registration, commercial licence, renewal and confirmation statement.
- ADGM family offices page, checked 9 November 2026. SPV fee USD 1,900; annual renewal USD 1,400; third-party provider fees vary.
- Federal Decree-Law No. 47 of 2022 on the Taxation of Corporations and Businesses, consolidated with amendments. Rates: Article 3. Qualifying free zone person: Article 18. Exempt UAE dividends: Article 22. Participation exemption: Article 23.
- Cabinet Decision No. 116 of 2022 on the annual taxable income subject to corporate tax (AED 375,000 threshold).
- Ministerial Decision No. 229 of 2025 on Qualifying Activities and Excluded Activities, effective from 1 June 2023, replacing Ministerial Decision No. 265 of 2023. Qualifying and excluded activities: Article 2. De minimis test: Article 3. Audited accounts condition: Article 5. Loss of status for five tax periods: Article 5(2).
- Ministerial Decision No. 302 of 2024 on the Participation Exemption and Foreign Permanent Establishment Exemption.
- Currency conversion at the UAE dirham peg of AED 3.6725 per USD.
Ancova Associates checked the fees, dates and rules on this page between 8 and 10 November 2026 against DMCC's SPVs and Holding Companies page, its announcement of 5 May 2025 and its List of Approved Activities, the DMCC Licensing Rules (version 3), the DMCCA Company Regulations, DMCC's schedule of charges, the DMCCA Foundations Regulations, the DIFC Registrar of Companies Table of Fees (Rev. 16), ADGM's 2025 schedule of fees and family offices page, Federal Decree-Law No. 47 of 2022 and Ministerial Decision No. 229 of 2025. Cover photo: Molochmeditates, Wikimedia Commons, CC BY-SA 4.0, cropped.
This article is general information, not legal or tax advice. Outcomes depend on your assets, your group and where each owner lives. Take advice from a qualified practitioner before acting.
Written by
Amine Derag
Director of Strategy, Ancova Associates
Amine Derag is Director of Strategy at Ancova Associates, the Dubai advisory firm for company formation, residency, citizenship by investment, and cross-border tax structuring. He advises founders and private clients relocating to the UAE on how a UAE structure interacts with their home-country tax and reporting obligations.
Connect on LinkedInThis article is general information for educational purposes only and is not legal, tax, financial, or immigration advice. Investment thresholds, processing times, and program terms change. Speak with a qualified Ancova adviser before acting.